
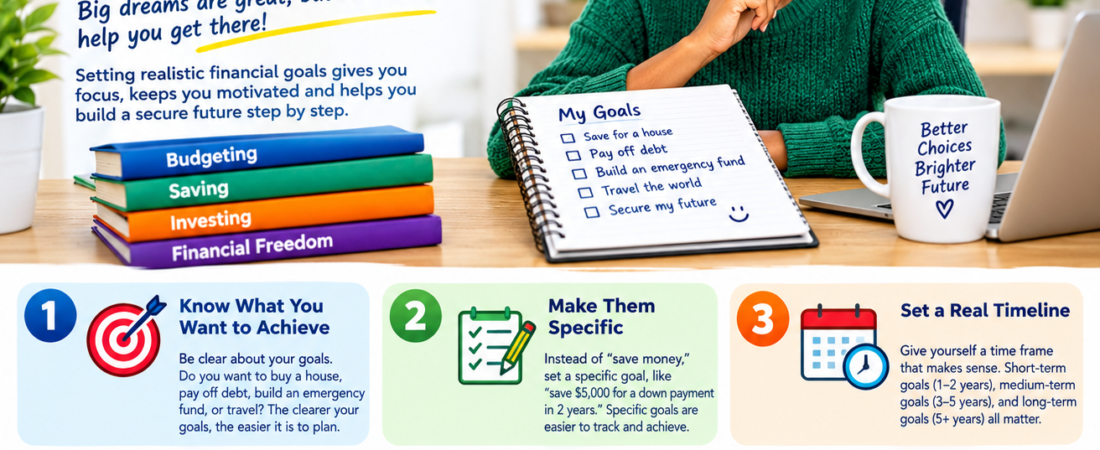
Setting financial goals is one of the simplest ways to take control of your money. Whether you want to build an emergency fund, pay off debt, save for a home, or simply stop living paycheck to paycheck, having a clear goal gives your money a purpose.
However, financial goals only work when they are realistic. Setting a goal that is too large or impossible to maintain can quickly become discouraging. The key is to create goals that match your income, expenses, priorities, and current financial situation.
Start by Understanding Your Current Finances
Before setting a financial goal, take an honest look at where you currently stand. Check your monthly income, regular expenses, debts, savings, and spending habits.
You do not need a complicated financial system. A simple list can help you understand how much money comes in each month and where it goes.
Knowing your starting point makes it easier to choose goals that are achievable.
Decide What You Want to Accomplish
Think about what you want your money to help you achieve. Your goals should reflect your personal priorities rather than what other people are doing.
Common financial goals include:
- Building an emergency fund
- Paying off credit card debt
- Saving for a car
- Saving for a home
- Starting an investment account
- Preparing for retirement
- Reducing unnecessary spending
- Building long-term savings
Choose goals that are meaningful to you.
Separate Short-Term and Long-Term Goals
Not every financial goal needs to happen immediately. Dividing goals into different time periods can make them easier to manage.
Short-term goals may take a few weeks or months, such as saving for a bill or paying off a small debt.
Medium-term goals may take one to five years, such as saving for a car or building a larger emergency fund.
Long-term goals may take many years, such as buying a home or preparing for retirement.
Having different types of goals helps you balance immediate needs with future plans.
Make Your Goals Specific
A vague goal such as “I want to save more money” is difficult to measure.
Instead, make the goal specific. For example, you could decide to save $2,000 for an emergency fund within 10 months.
A specific goal tells you exactly what you are trying to accomplish and gives you a target to work toward.
Make Your Goals Measurable
A good financial goal should have a number attached to it whenever possible.
For example:
- Save $100 every month
- Pay off $1,500 of debt
- Build a $3,000 emergency fund
- Reduce monthly eating-out expenses by $75
Measurable goals allow you to see your progress and make adjustments when necessary.
Give Every Goal a Deadline
A deadline creates a sense of direction. Without one, it is easy to keep postponing your goal.
For example, instead of saying, “I want to save for a vacation,” choose a target date and calculate how much you need to save each month.
If you need $1,200 in 12 months, saving approximately $100 per month gives you a clear plan.
Make Sure the Goal Fits Your Income
One of the biggest mistakes people make is setting financial goals without considering their actual income.
If you earn $3,000 per month and your essential expenses already take up most of your income, trying to save $1,000 every month may not be realistic.
Instead, start with an amount you can consistently afford. Even a smaller amount can make a difference when you maintain it over time.
Break Big Goals Into Smaller Steps
Large financial goals can feel overwhelming. Breaking them into smaller milestones makes them easier to handle.
For example, if your goal is to build a $5,000 emergency fund, you could divide it into smaller targets:
- First $500
- Then $1,000
- Then $2,500
- Finally $5,000
Each milestone gives you something achievable to work toward.
Prioritize Your Goals
You may have several financial goals at the same time, but trying to accomplish everything at once can make your finances difficult to manage.
Start by identifying what is most important.
For example, you might prioritize building a basic emergency fund and paying high-interest debt before putting more money toward less urgent goals.
Your priorities can change as your financial situation changes.
Create a Monthly Action Plan
A goal becomes much easier to achieve when you turn it into a regular habit.
If you want to save $1,200 in one year, for example, you could set aside about $100 each month.
Consider treating your savings goal like a regular bill. Put the money aside shortly after receiving your income instead of waiting until the end of the month.
Automate Your Savings
Automation can make saving easier because you do not have to remember to move the money manually every month.
If your bank allows automatic transfers, you can schedule a certain amount to move from your checking account to your savings account on a regular basis.
Make sure the transfer amount fits comfortably within your budget.
Plan for Unexpected Expenses
Real life does not always follow a budget. Car repairs, medical bills, home repairs, or other unexpected expenses can interrupt your plans.
This is why an emergency fund is an important financial goal for many people.
Having money set aside for unexpected costs can help prevent one financial surprise from completely disrupting your other goals.
Track Your Progress
Check your goals regularly. You do not need to monitor them every hour, but a weekly or monthly review can help you stay aware of your progress.
Ask yourself:
- How much have I saved?
- How much debt have I paid off?
- Am I staying within my spending limits?
- Is my current plan still realistic?
- Do I need to make adjustments?
Tracking your progress also helps you recognize improvements that might otherwise go unnoticed.
Adjust Your Goals When Your Situation Changes
A realistic financial goal is not necessarily permanent.
Your income may increase or decrease. Your expenses may change. You may experience an unexpected expense or discover a new financial priority.
If your original goal no longer fits your situation, adjust it rather than giving up completely.
For example, if you planned to save $300 per month but your expenses temporarily increase, you might reduce the amount to $150 and continue building the habit.
Avoid Comparing Your Goals With Other People
Everyone’s financial situation is different. Comparing your progress with friends, family members, influencers, or people online can create unrealistic expectations.
Someone else’s income, expenses, debt, savings, or financial support may be completely different from yours.
Focus on improving your own financial position rather than trying to match someone else’s lifestyle.
Celebrate Small Wins
Financial progress does not always happen quickly. Recognizing smaller achievements can help you stay motivated.
Paying off a credit card, reaching your first $500 in savings, sticking to your budget for three months, or reducing unnecessary spending are all meaningful steps.
Celebrating does not have to mean spending a lot of money. Simply recognizing your progress can help you maintain good habits.
Review Your Goals Regularly
Set aside some time every few months to review your financial goals.
You may discover that one goal is progressing faster than expected while another needs more time. You might also have new priorities that deserve attention.
Regular reviews allow your financial plan to grow with you instead of becoming an outdated list.
Keep Your Financial System Simple
You do not need dozens of accounts, complicated spreadsheets, or complicated rules to set realistic goals.
A simple system can work well:
- Choose a clear goal.
- Set a realistic amount.
- Choose a deadline.
- Break it into monthly targets.
- Automate savings when possible.
- Track your progress.
- Adjust when necessary.
The simpler your system is, the easier it may be to maintain.
Final Thoughts
Setting realistic financial goals is about creating a plan that works with your actual life. Start by understanding your current finances, choose goals that matter to you, make them specific, and break large targets into smaller steps.
You do not need to make huge financial changes overnight. Consistent progress, even when it is small, can help you build stronger financial habits over time. The most important thing is to create goals you can realistically follow and review them as your circumstances change.